

For more than two decades, an unusual form of home financing has operated inside the American mortgage market.
It is designed to comply with Islamic prohibitions on riba, commonly understood as interest. Its architects describe it not as a conventional loan, but as a declining co-ownership arrangement in which the homebuyer gradually purchases the financier’s share of the property.
Yet the structure does not sit outside America’s mortgage system.
It was deliberately engineered to enter it.
Freddie Mac’s own securities documentation recognizes financing arrangements that may take forms other than ordinary mortgage notes while still being treated as mortgages within its system — including arrangements “designed to comply with Islamic law” (p. 38).
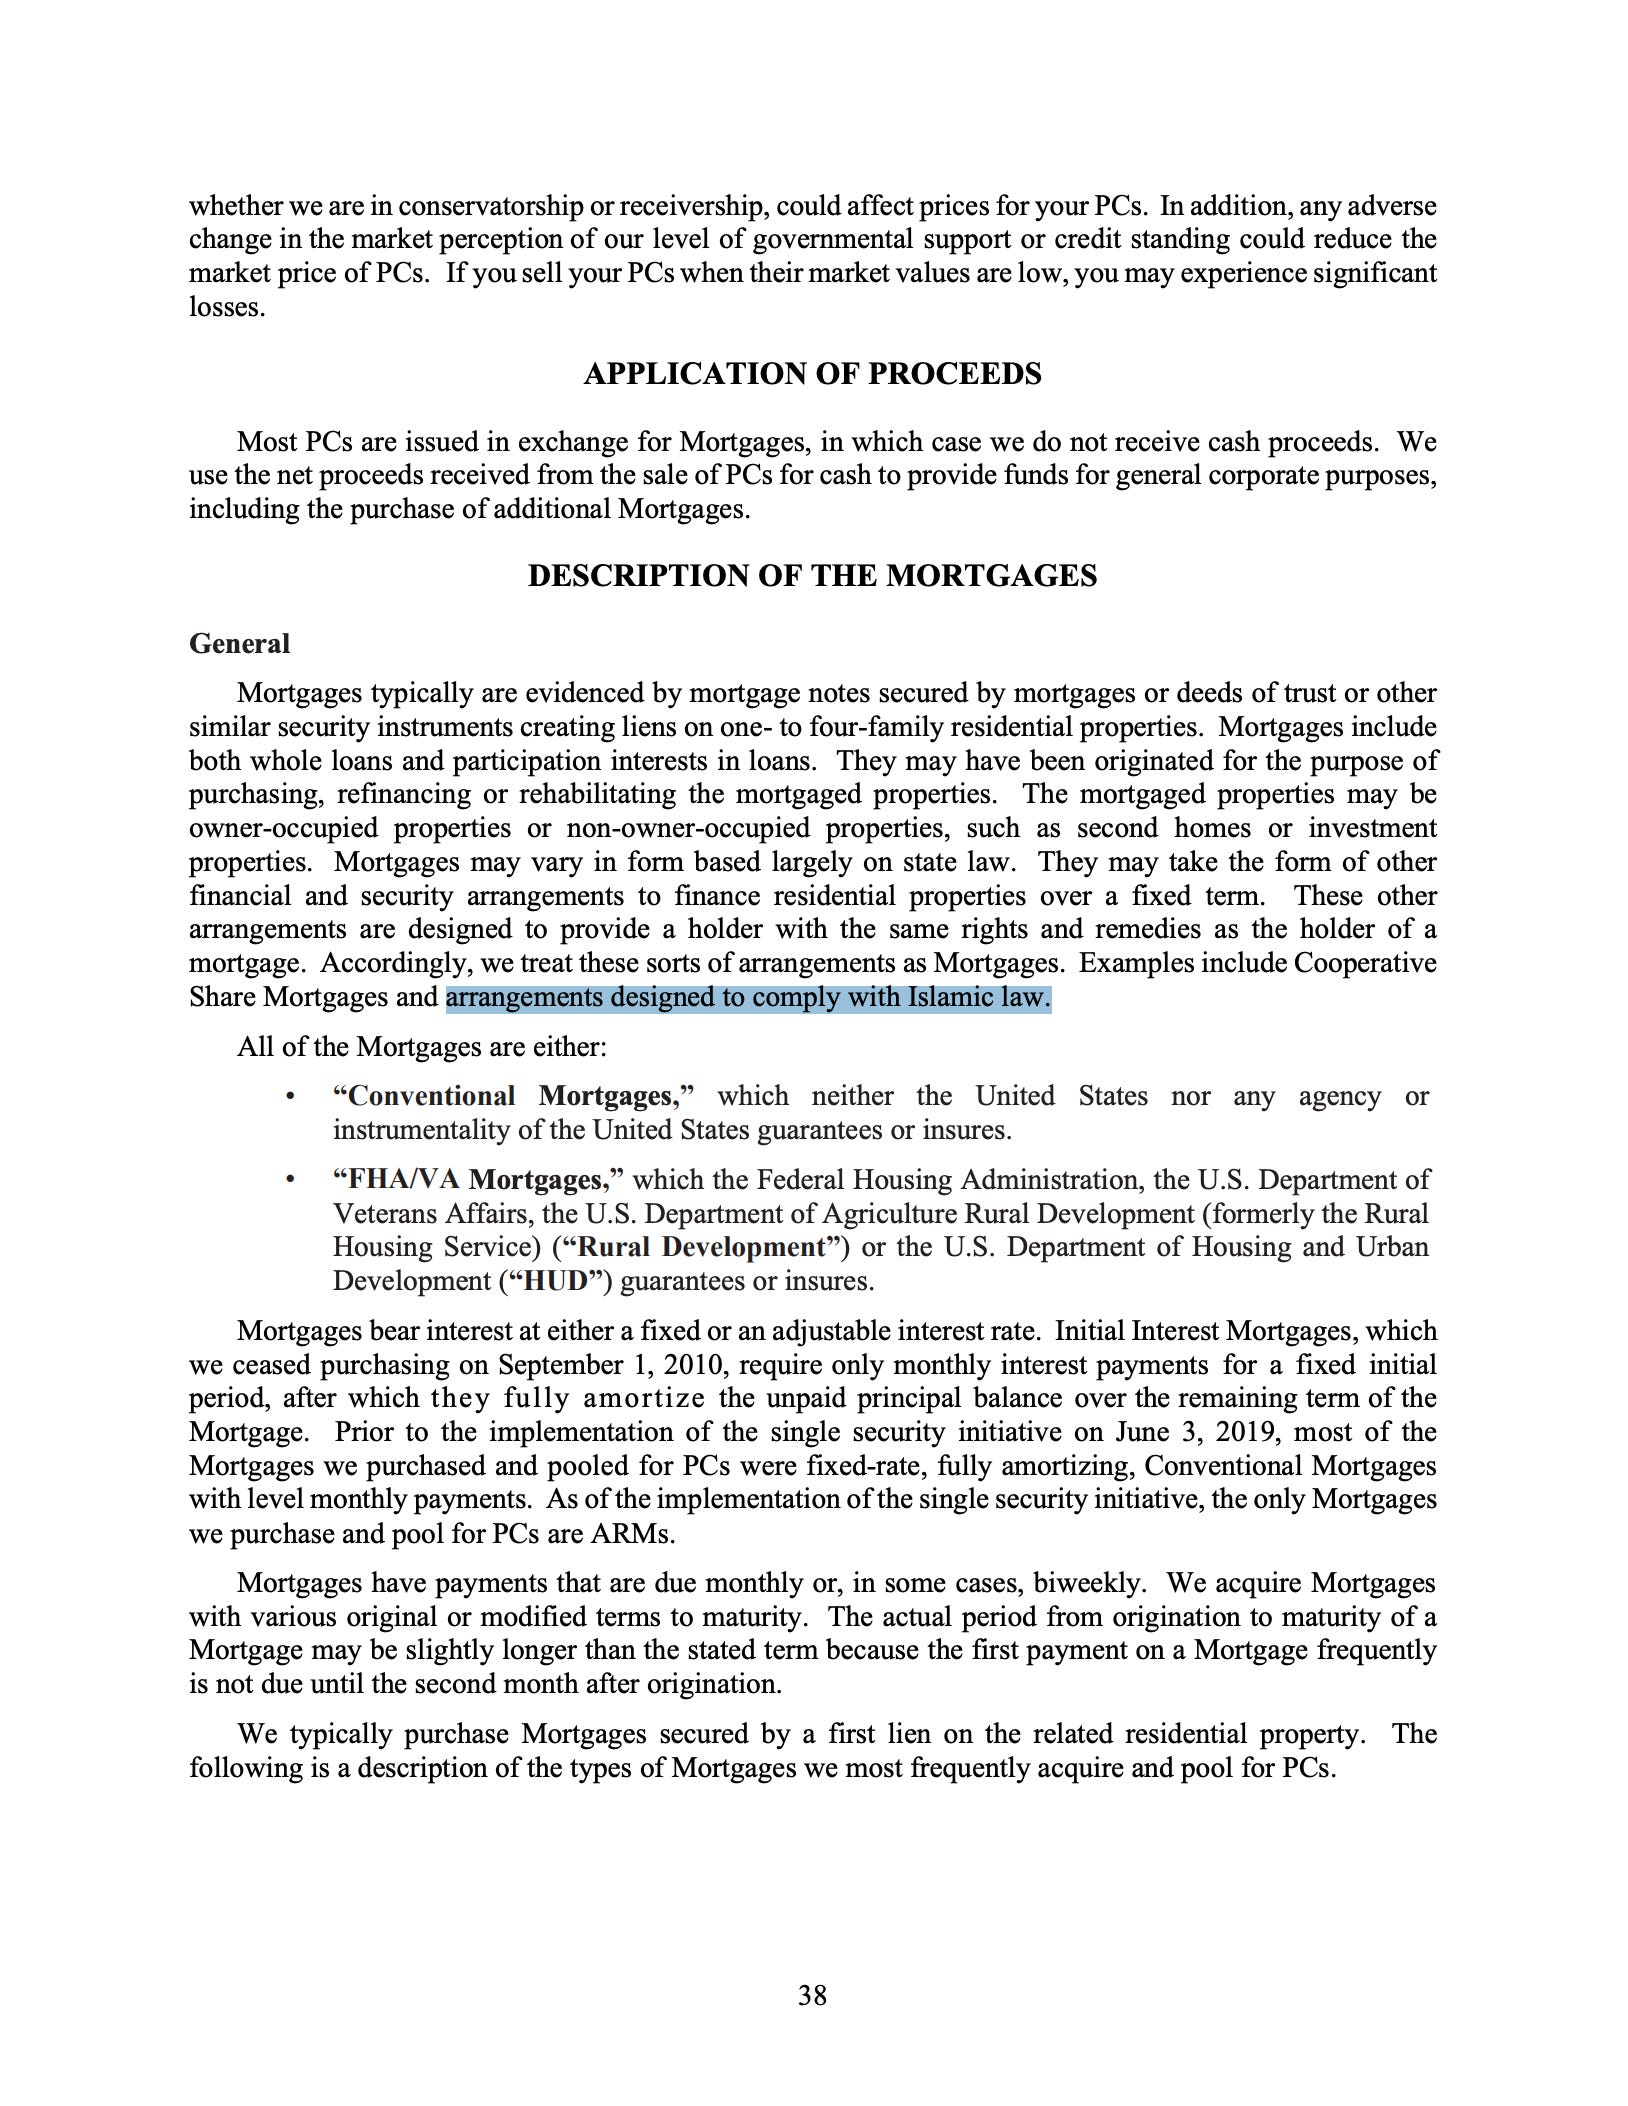
That sentence is the doorway into a financial structure that took years of legal, religious and mortgage-market engineering to build.
And in August 2026, the head of the agency overseeing Fannie Mae and Freddie Mac said officials were looking into it.
Prefer video? Watch the full breakdown here:
The 2026 Review
On August 13, 2026, FHFA Director William Pulte, who also chairs the boards of Fannie Mae and Freddie Mac, responded to a post raising the issue of Sharia-compliant home financing:
“We are looking into this right now. Thanks for mentioning!”


As of publication, we found no public FHFA order terminating or suspending Sharia-compliant financing.
What exists is a public statement that the matter is under review.
And the system being reviewed is not new.
Built for Two Systems
Guidance Residential, one of the largest Islamic home-finance providers in the United States, says its model emerged from a three-year research effort involving 18 law firms and Islamic-finance scholars.
The goal was specific: create a home-finance structure that could comply with American law and Islamic jurisprudence at the same time.
Guidance calls the result a Declining Balance Co-Ownership Program, or diminishing Musharakah.
Instead of describing the transaction as an interest-bearing loan, Guidance and the consumer acquire interests in the home. The consumer then makes payments that gradually increase the consumer’s ownership share while reducing the financier’s share.
Guidance says the program has now provided more than $10 billion in financing to more than 40,000 families.
The religious requirements were not added after the fact.
They were part of the product’s design from the beginning.
The Human Architects
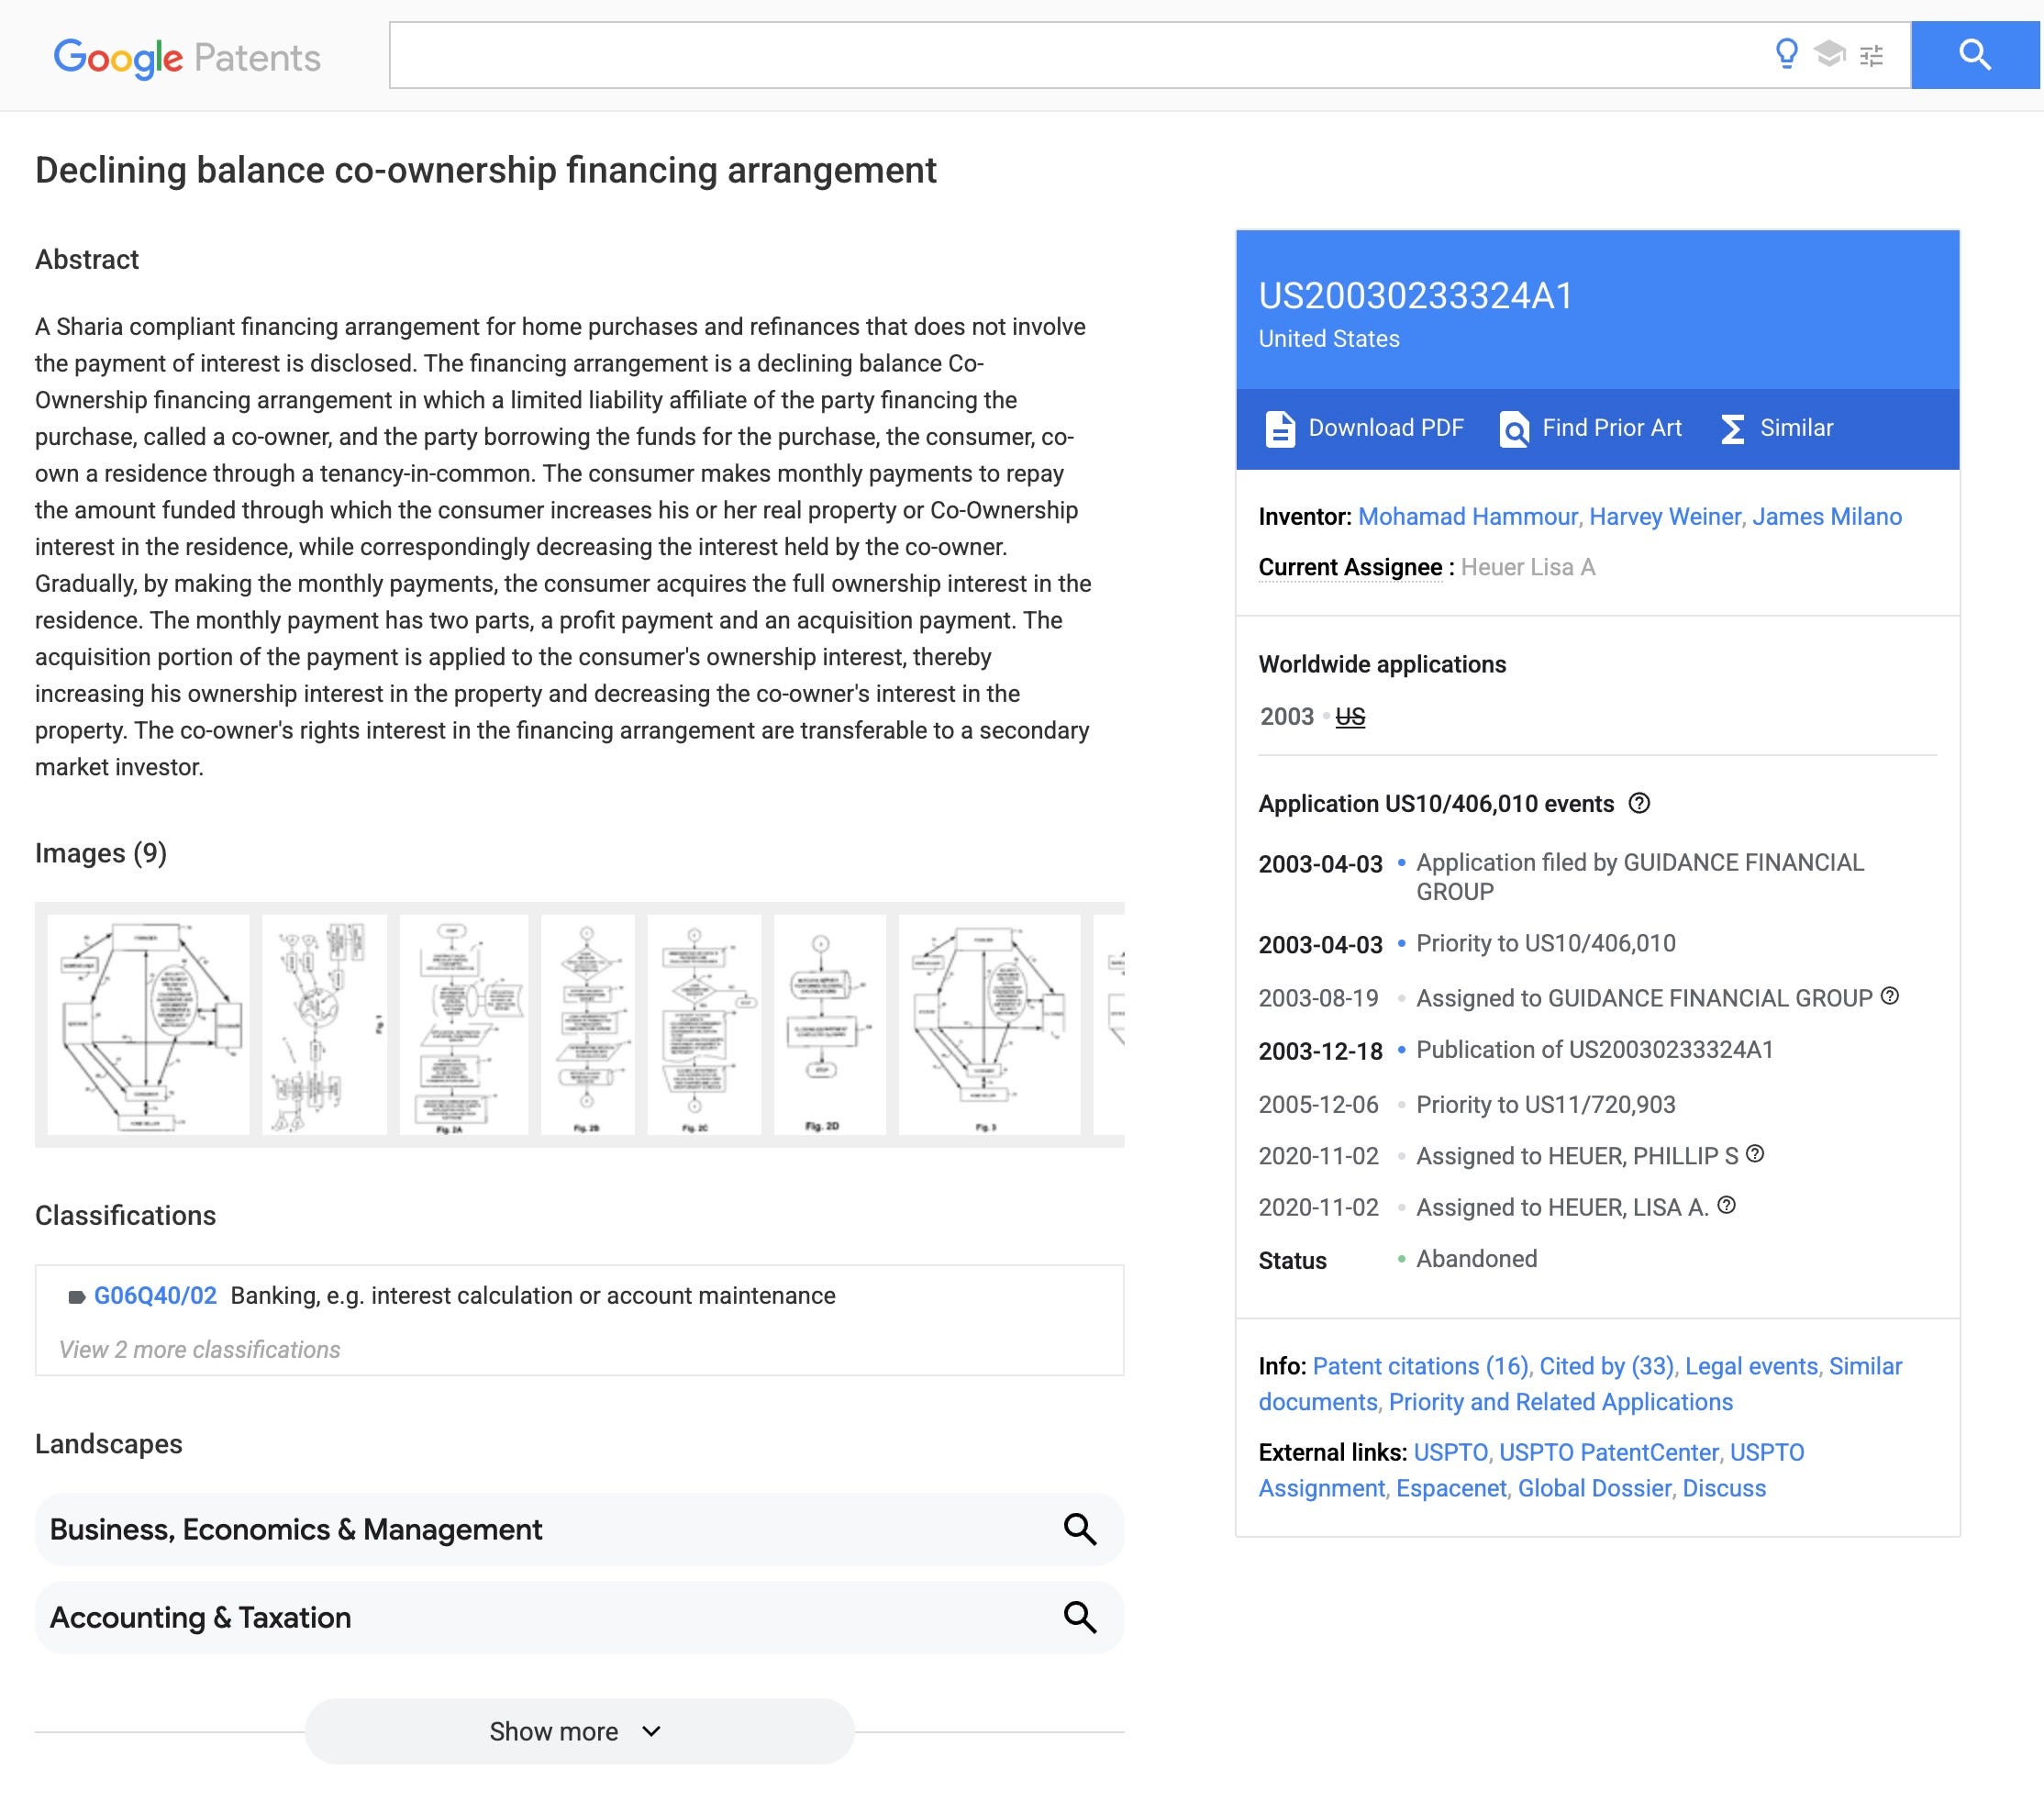
A 2003 U.S. patent application titled “Declining balance co-ownership financing arrangement” names three inventors:
Mohamad Hammour
Harvey Weiner
James Milano
The original assignee was Guidance Financial Group.
The patent explains that the objective was to create financing that avoided interest payments while remaining compatible with taxation, U.S. property law and the secondary mortgage market.
It explicitly contemplates a secondary-market investor such as Freddie Mac, Fannie Mae, or an investment banker.
In other words, secondary-market compatibility was not an accidental later development.
It was part of the architecture.
What the Government Record Says
A 2005 Massachusetts Department of Revenue ruling examined the Guidance co-ownership model in detail.
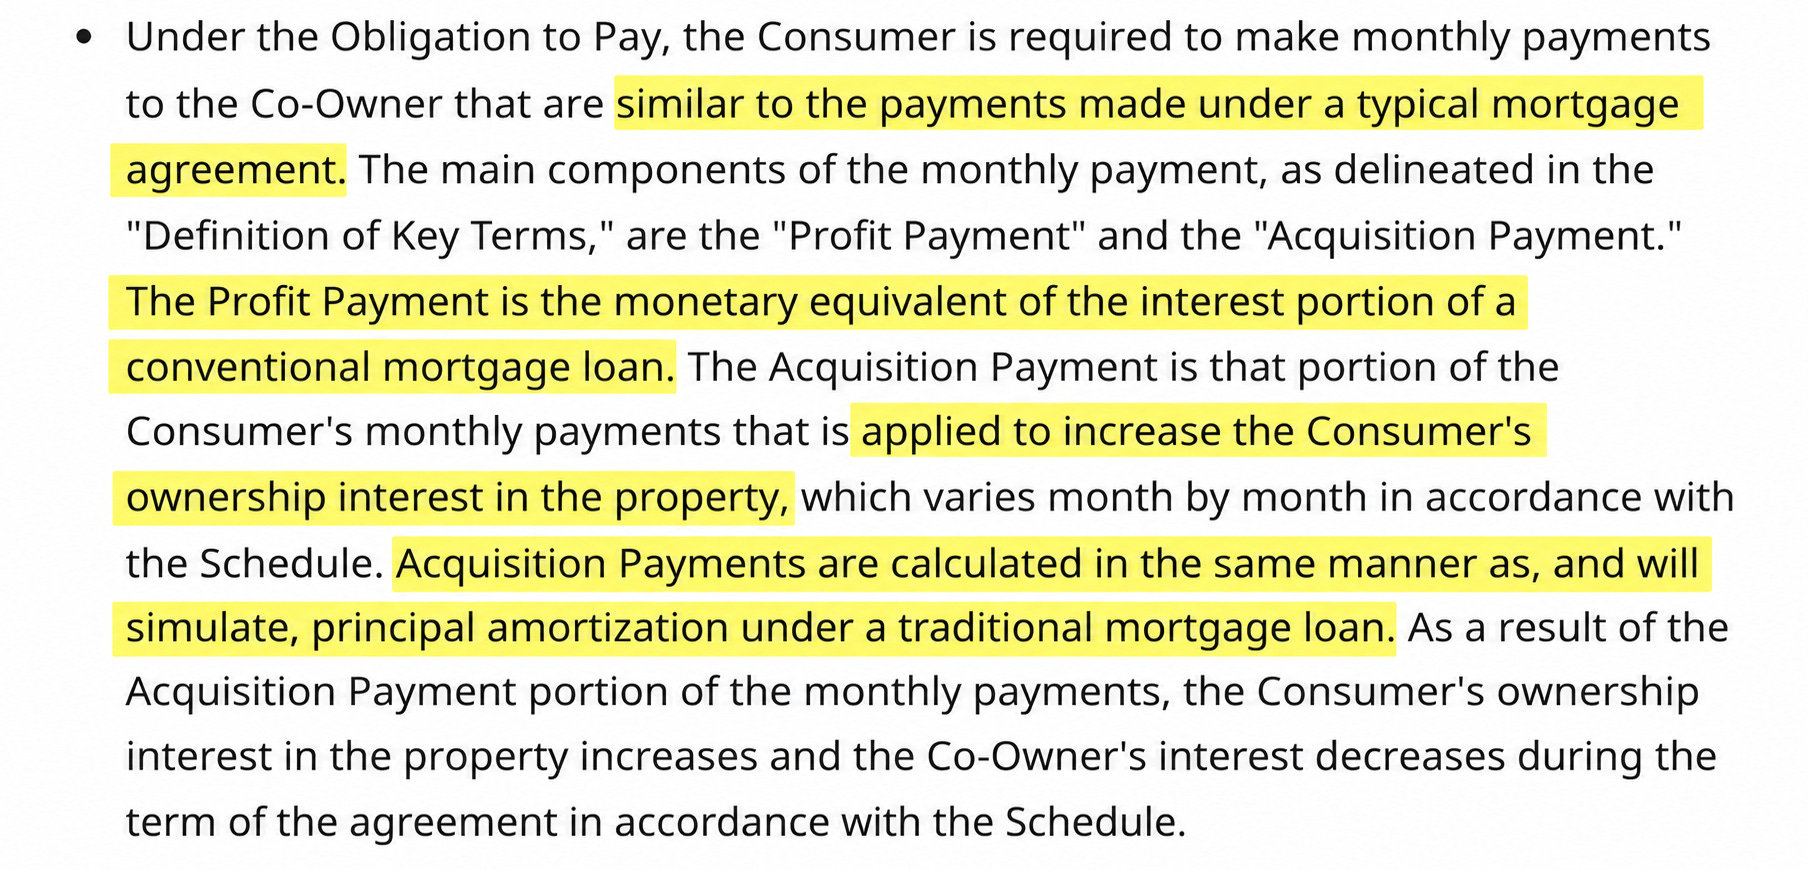
It describes the customer making two types of monthly payments: a Profit Payment and an Acquisition Payment.
The state says the profit portion is the monetary equivalent of the interest component of a conventional mortgage, while the acquisition portion functions similarly to principal amortization.
The same ruling follows the transaction into the secondary market.
The co-owner’s interests under the co-ownership agreement, obligation to pay and security instrument are assigned to the financier, which then transfers its interests to Freddie Mac.
The ruling says Freddie treats the arrangement “in a manner similar to other mortgage transactions in its system.”
That may be the cleanest description of the entire interface.
Religiously, the product is structured as co-ownership.
Operationally, Freddie processes it in a mortgage-like system.
The Special Interface
Guidance says it worked with Freddie Mac and 18 law firms for three years to create a structure under which Freddie could participate without the transaction being characterized by Guidance as a prohibited sale of debt.
Guidance describes Freddie as acquiring an investment interest in the co-ownership structure while Guidance continues administering the homeowner agreement under Islamic financial principles.
Guidance also says it is the only U.S. provider permitted to deliver its specific Declining Balance Co-Ownership structure to Freddie Mac.
That is the institutional story.
Islamic jurisprudence established the religious constraints.
American lawyers built the documents.
The federal mortgage market supplied the liquidity.
The “Shariah Transaction Amendment”
The public bankruptcy record adds another unusual receipt.
Residential Capital contract schedules identify a Guidance Residential Client Contract dated August 22, 2005.
A later entry identifies an amendment dated August 17, 2006:
“Shariah Transaction Amendment.”
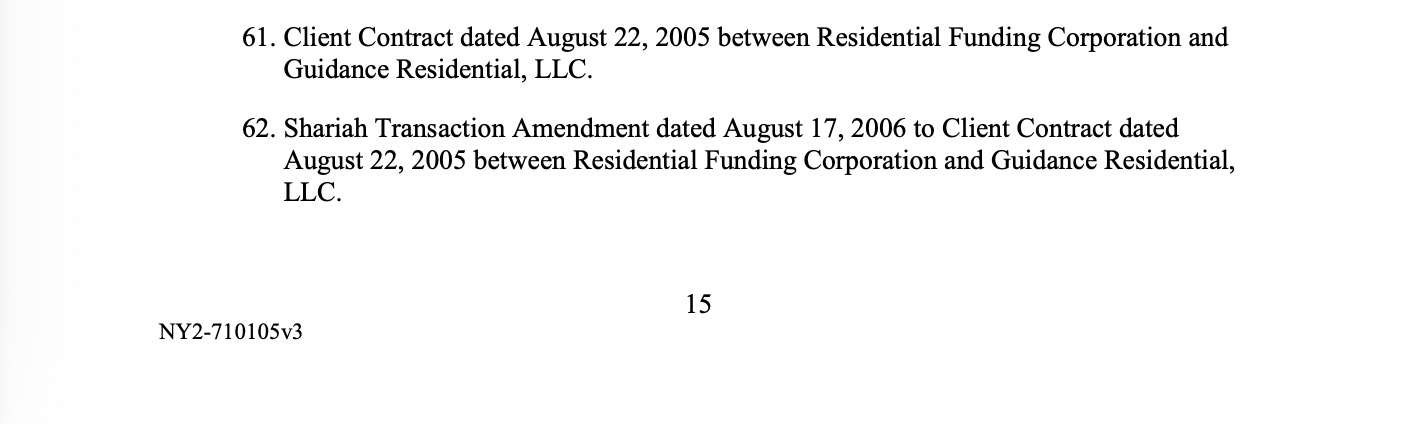
The public record proves the amendment existed.
It does not reveal the full amendment’s substantive provisions, and we have not located a public copy of the entire agreement.
That means we can document that a specifically named Shariah amendment was attached to a conventional mortgage-market client contract.
We cannot yet say exactly what clauses it changed.
Still American Mortgage Plumbing
None of this means Islamic law replaced American mortgage law.
The transaction still uses familiar U.S. financial instruments: security documents, assignments, servicing arrangements, disclosures, underwriting and foreclosure remedies.
The patent itself contemplates federal mortgage disclosures and property pledged as collateral.
A 2005 Federal Reserve Bank of New York speech also discussed Fannie Mae and Freddie Mac participation in Sharia-compliant home finance while describing the products as operating within existing American banking and regulatory requirements.
The U.S. financial system did not disappear.
It adapted the interface.
Is the Buyer Getting a Special Deal?
This is where the viral version of the story often becomes misleading.
We found no evidence that someone receives a special government interest-rate subsidy simply because they choose Sharia-compliant financing.
Guidance says its profit rate is benchmarked to prevailing market rates.
There can be contractual differences — Guidance advertises features such as non-recourse treatment, limited late fees, no prepayment penalty and certain risk-sharing provisions.
But those are not evidence of free or specially discounted federal financing.
The major economic advantage is more structural:
secondary-market liquidity.
A specialized financing company cannot leave its own capital tied up in homes for decades and continue expanding rapidly.
Fannie Mae and Freddie Mac access allows capital to be recycled into more transactions.
That is how a specialized religious-finance model becomes scalable.
Two Languages, One Transaction
The same transaction can be described in two different vocabularies.
Inside the Islamic-finance framework:
co-ownership
profit payment
acquisition payment
Musharakah
no riba
Inside the American mortgage system:
security instrument
assignment
servicing
underwriting
secondary-market investor
foreclosure
Both descriptions can be true because the contract was deliberately designed to function inside both systems.
That is the architecture.
Why It Matters Now
The arrangement has existed for more than two decades.
The patent shows that secondary-market access was contemplated during the product’s design.
State regulators documented how the structure moves into Freddie Mac’s system.
Freddie’s own securities materials expressly recognize financing arrangements designed to comply with Islamic law.
And a bankruptcy schedule preserves the existence of a “Shariah Transaction Amendment.”
Now, in August 2026, FHFA’s director says federal officials are examining the issue.
No public termination order has been announced.
But something that operated largely outside the political spotlight has suddenly become a live federal policy question.
The Contract Beneath the Mortgage
The evidence does not support the simplistic claim that America “adopted Sharia law.”
Something more precise happened.
A privately designed financial product whose defining constraints came from Islamic jurisprudence was translated into American mortgage instruments and given access to the federally supported secondary housing market.
Islamic scholars defined the religious requirements.
Lawyers translated those requirements into American contracts.
Mortgage professionals built the security, servicing and secondary-market machinery.
And institutions such as Freddie Mac provided the liquidity necessary for the system to operate at scale.
That architecture existed for more than twenty years before most Americans ever heard about it.
Now Washington is looking.
The question is no longer whether the system exists.
The documents show that it does.
The question is what federal officials decide to do with it next.
The Alignment Archive examines public records, institutional structure, financial architecture and the decision systems beneath visible events. This dossier relies on Freddie Mac materials, state regulatory records, Federal Reserve records, U.S. patent filings, bankruptcy documents and the provider’s own published materials.
Read the permanent Field Dossier and source trail:
The Contract Beneath the Mortgage
Public record. Follow the documents.